As of the original report on November 17, 2026, at 08:38 UTC+8, Bitcoin had fallen from about $80,000 to $62,000 over ten days. What was driving the decline? On-chain analyst Yu Jin argued that it was a combination of spot selling, thin liquidity and leveraged positions—not a single event or market participant.
Yu Jin said MARA had sold 40,581 BTC so far that year, worth about $3.02 billion. He also cited roughly $3 billion in net outflows from spot Bitcoin ETFs over the preceding two weeks, which he estimated created about $300 million in selling pressure per business day. In his account, weak trading activity and high futures open interest made the market more vulnerable: spot sales could trigger leveraged-position closures and deepen the fall. He said the decline accelerated after a long position worth more than $500 million was liquidated on Hyperliquid on November 12.
Options positioning had shifted, too. On Deribit, the $60,000 put had about $900 million in notional open interest, slightly above the $867 million in the $100,000 call that had previously held the top spot. CoinDesk reported that the 30-day Bitcoin implied-volatility index, BVIV, briefly reached 57.13 on Sunday—its highest level since June—before easing to 44.
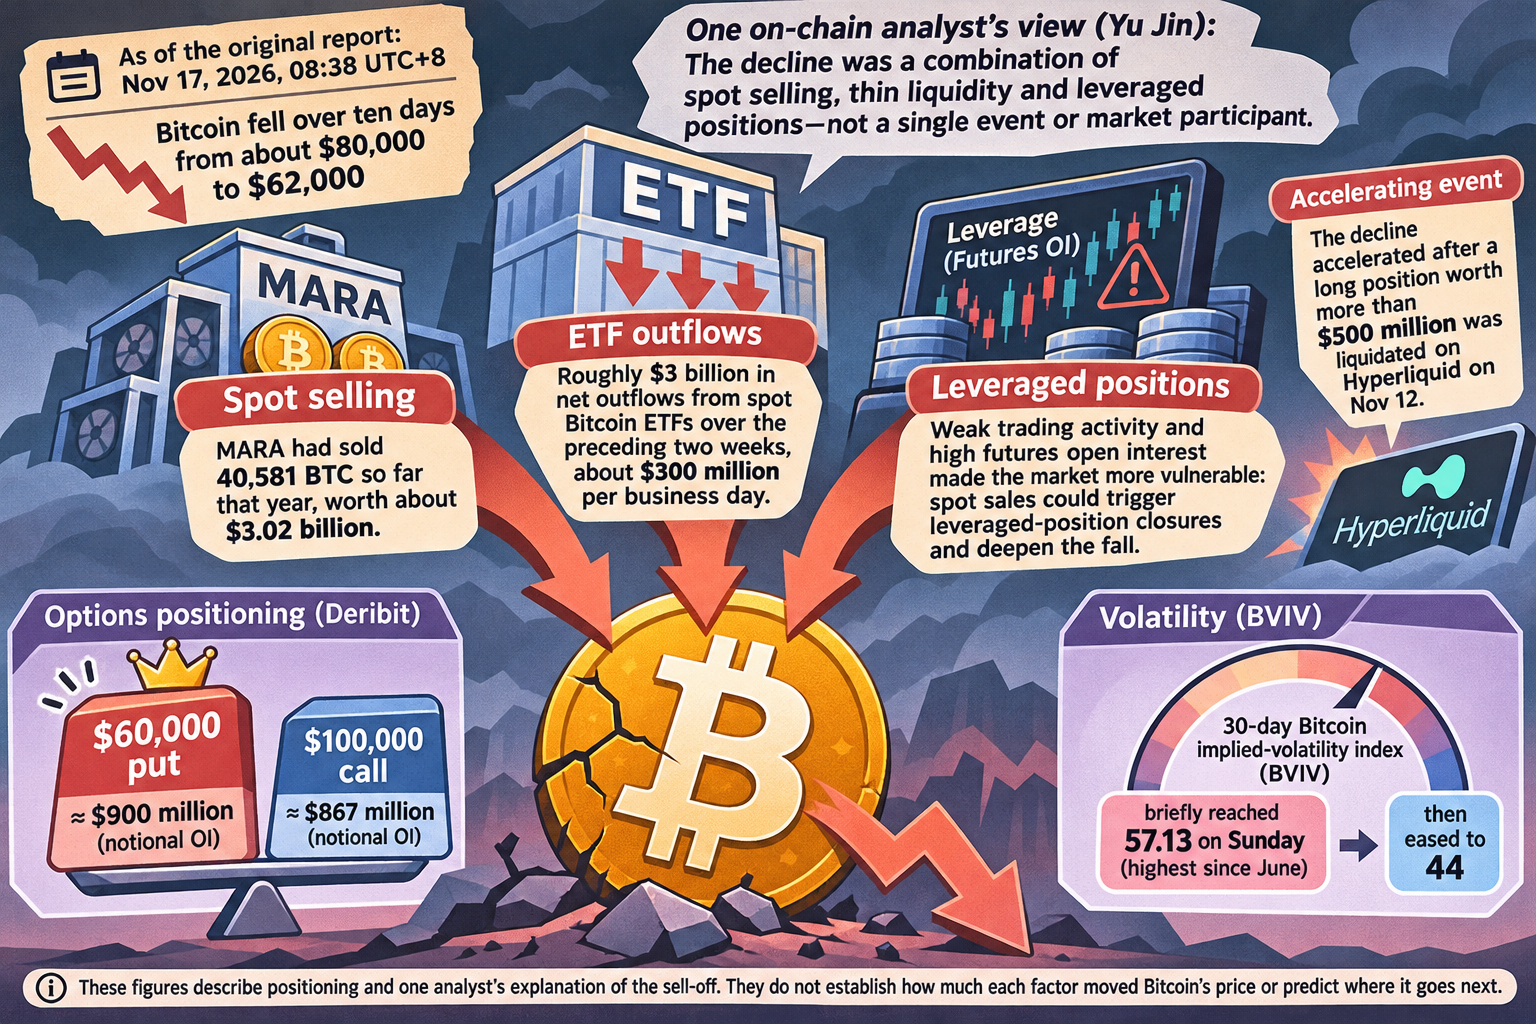
These figures describe positioning and one analyst’s explanation of the sell-off. They do not establish how much each factor moved Bitcoin’s price or predict where it goes next.